Can you get live-in care on the NHS? How funding works
Sometimes. Explore NHS and council funding, Attendance Allowance and paying privately in England, with a visual guide to where to start.
By the AnnMarie’s Care team
Published —7 min read
Updated
Short answer. Sometimes. NHS Continuing Healthcare can fund an agreed care package at home for eligible adults. Eligibility does not automatically guarantee a particular live-in provider or arrangement. Other routes include council support after assessment, private payment and benefits such as Attendance Allowance.
When a parent needs help at home, the first question most families ask is who pays. In England, explore NHS funding, council support and paying privately, alongside benefits such as Attendance Allowance. Check how these interact before making a plan. Figures below are for England in the 2026/27 financial year.
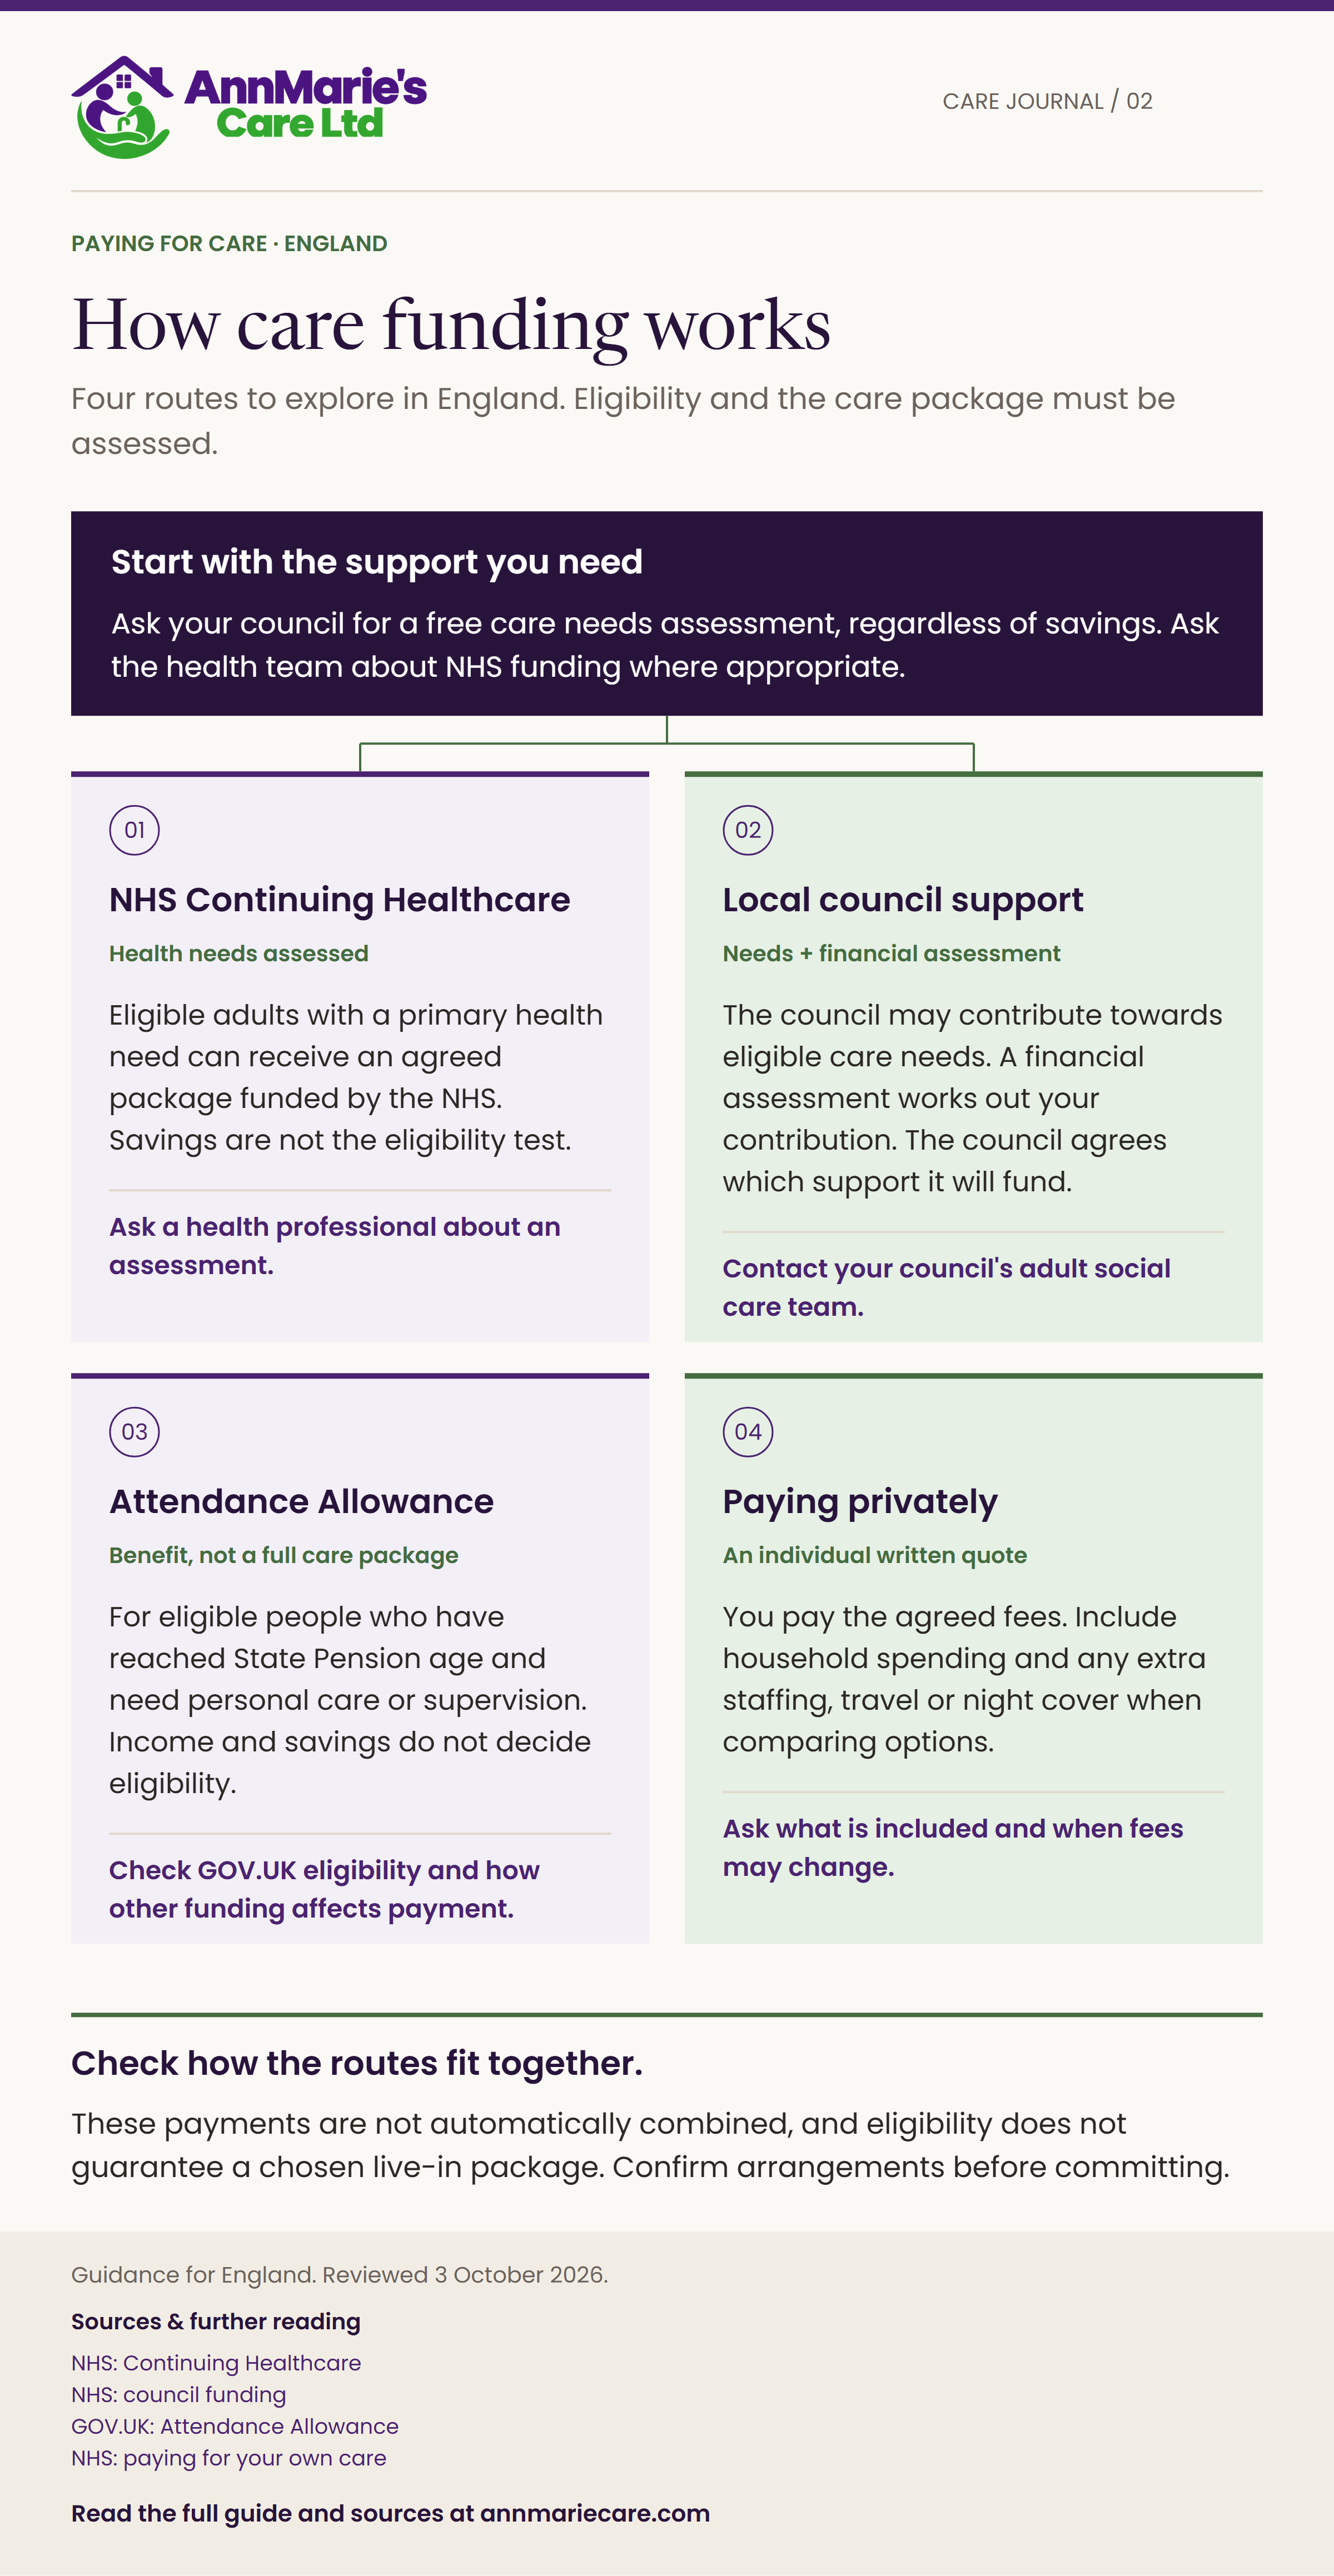
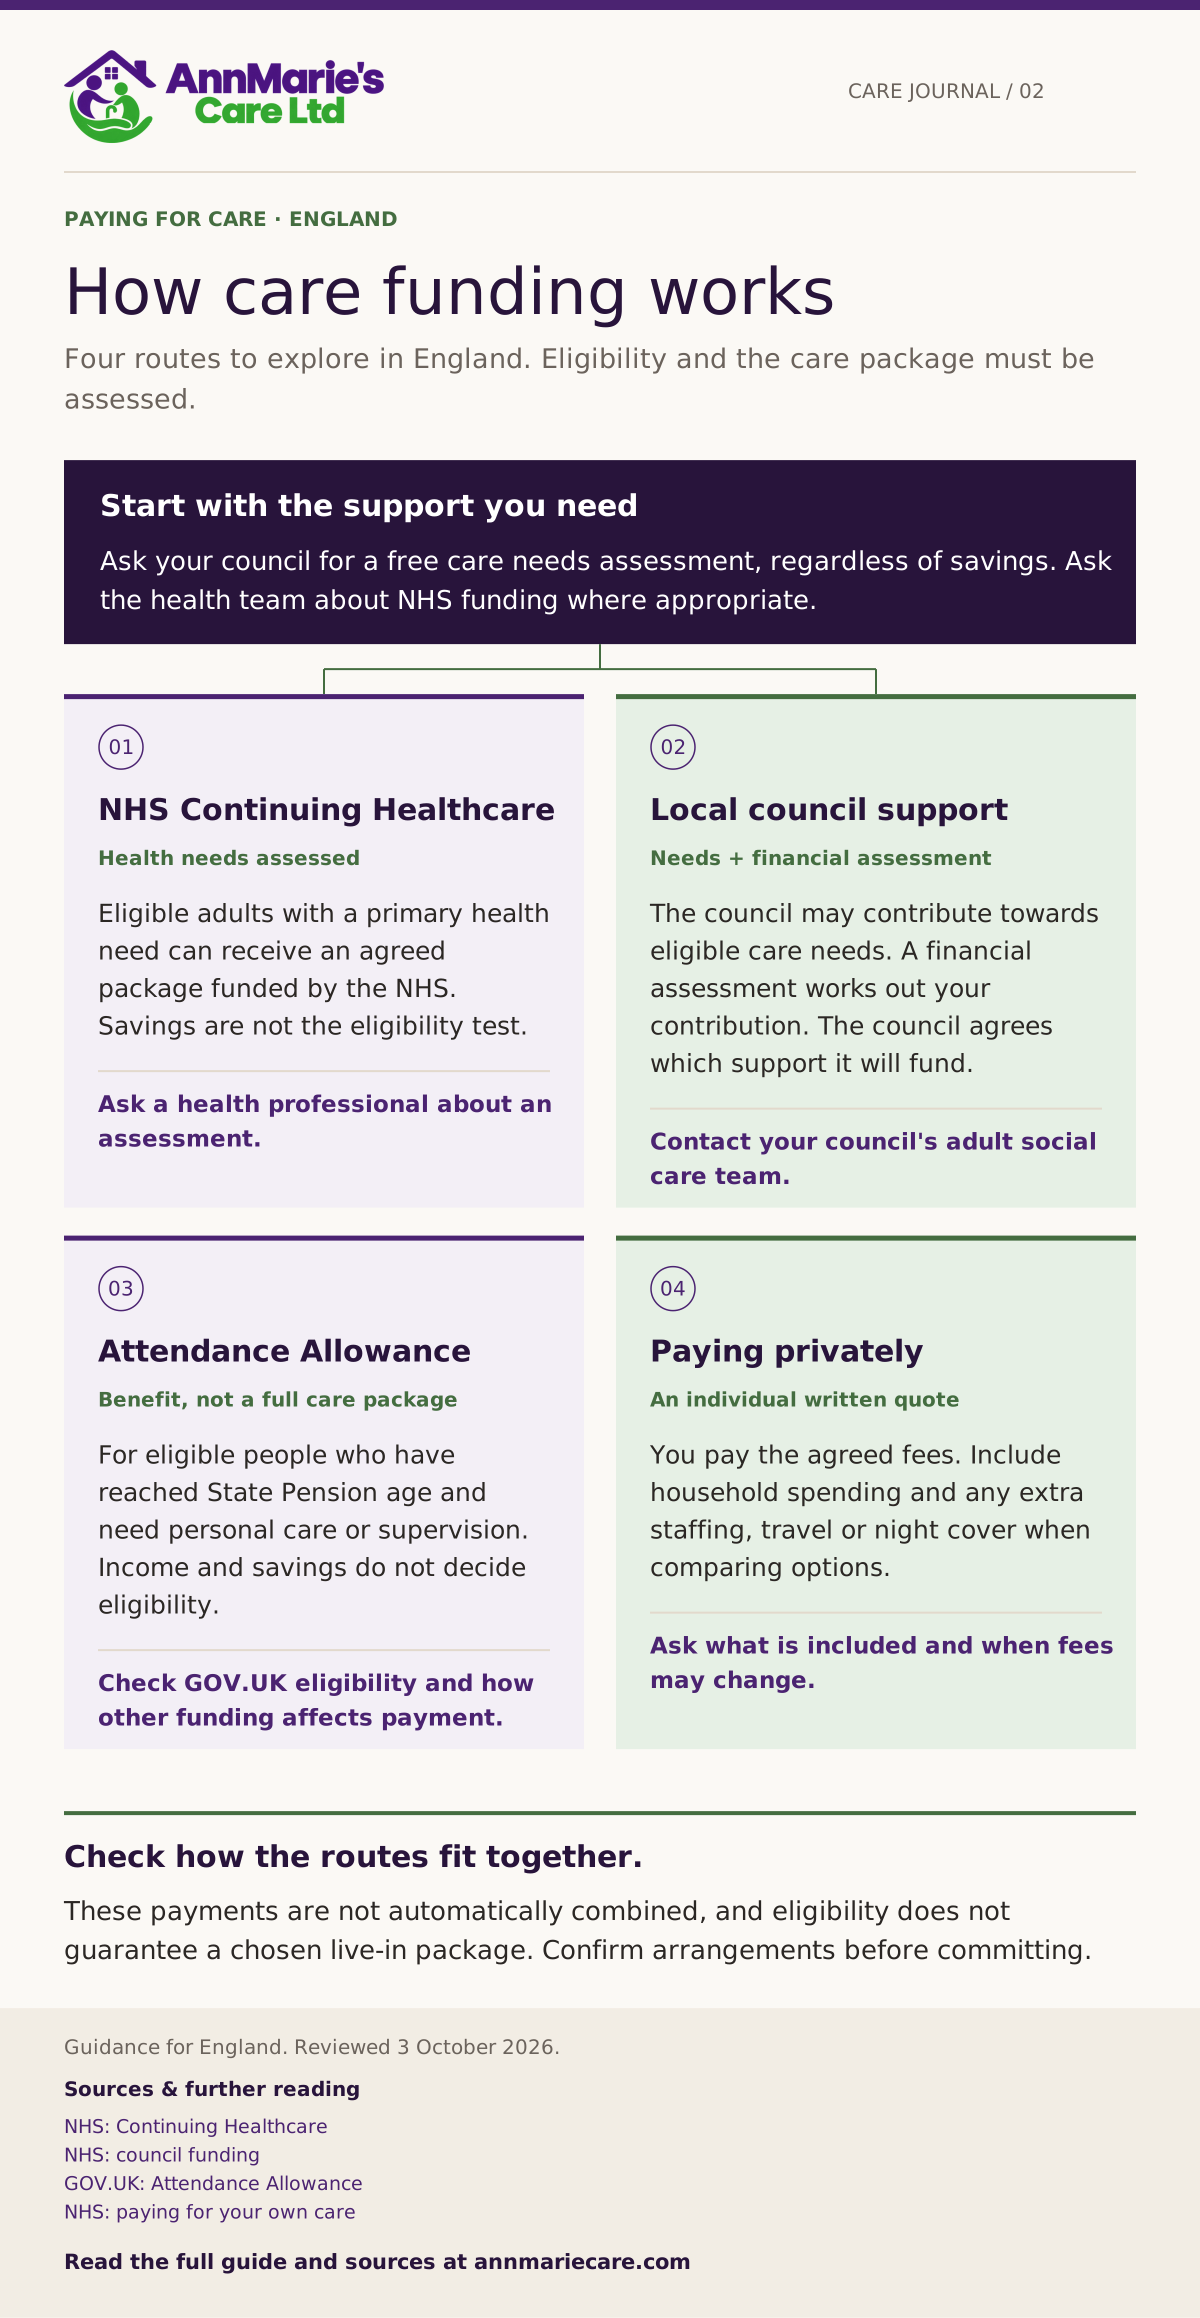
 Care Journal 02
Paying for care England
How care funding works
Four routes to explore in England. Eligibility and the care package must be assessed.
Start with the support you need
Ask your council for a free care needs assessment, regardless of savings. Ask the health team about NHS funding where appropriate.
NHS Continuing Healthcare
Health needs assessed
Eligible adults with a primary health need can receive an agreed package funded by the NHS. Savings are not the eligibility test.
Ask a health professional about an assessment.
Local council support
Needs + financial assessment
The council may contribute towards eligible care needs. A financial assessment works out your contribution. The council agrees which support it will fund.
Contact your council's adult social care team.
Attendance Allowance
Benefit, not a full care package
For eligible people who have reached State Pension age and need personal care or supervision. Income and savings do not decide eligibility.
Check GOV.UK eligibility and how other funding affects payment.
Paying privately
An individual written quote
You pay the agreed fees. Include household spending and any extra staffing, travel or night cover when comparing options.
Ask what is included and when fees may change.
1. NHS Continuing Healthcare (fully funded by the NHS)
NHS Continuing Healthcare, often shortened to CHC, is a package of care paid for entirely by the NHS. It is not means-tested, so savings and the family home make no difference. It can pay for care in your own home, including live-in care.
To qualify, a person must have a “primary health need”. This is assessed by considering the nature, intensity, complexity and unpredictability of their needs as a whole. It is not decided by diagnosis alone or by simply counting medical tasks.
The process usually runs like this:
- Checklist. A nurse, doctor or social worker completes a short screening tool. Ask your GP, district nurse, social worker or the hospital discharge team for one.
- Full assessment. A team of professionals gathers evidence about physical health, mental health and care needs, and completes the Decision Support Tool. You and your family can take part.
- Decision. Your local Integrated Care Board (ICB) makes the decision. The usual timescale is 28 days after the ICB receives the completed checklist or request for a full assessment, although exceptions can apply.
If eligible, the person can discuss a personal health budget and how their assessed needs will be met. A suitable home arrangement is agreed with the ICB; CHC does not mean any privately chosen package will be paid for.
If someone is rapidly deteriorating and may be approaching the end of life, ask the clinical team whether the fast-track pathway is appropriate. Do not wait for a routine checklist.
NHS-funded nursing care is a different, smaller payment. It only applies to people living in a nursing home, so it does not help with live-in care.
2. Help from the local council
Anyone who appears to need care can ask their council for a free needs assessment under the Care Act 2014. If the council agrees there are eligible needs, it carries out a financial assessment to work out what your relative pays.
| Savings and capital | What happens (England, 2026/27) |
|---|---|
| Over £23,250 | Usually self-funding under the standard capital rules. |
| £14,250 to £23,250 | Eligible needs may receive support, with assessed income and a tariff on capital taken into account. |
| Under £14,250 | No tariff on capital; an assessed income contribution may still apply. |
These are the standard limits. Councils may set higher capital limits for care at home; support depends on both the needs and financial assessments.
Two points to discuss with the council:
- When care is provided in your relative's own home, the value of the home is not counted.
- The base Minimum Income Guarantee is £241.45 a week for a single person who has reached Pension Credit age in 2026/27. Different rates and additions apply to other circumstances. Ask how your own assessment protects living costs.
Councils fund the care they assess as necessary, at their own rates. That may cover visiting carers rather than a full live-in package, so some families pay the difference themselves. The council can pay its share as a direct payment, which gives you more choice over who provides the care. Ask your council how a direct payment can be used before you commit to an arrangement.
3. Attendance Allowance (not means-tested)
Attendance Allowance in England is for eligible people who have reached State Pension age and need personal care or supervision. Income and savings do not affect it, and it can be spent on anything, including live-in care.
| Rate | Who it is for | Weekly amount 2026/27 |
|---|---|---|
| Lower | Help needed during the day or at night | £76.70 |
| Higher | Help needed during the day and at night, or terminally ill | £114.60 |
Having a live-in carer does not itself determine the rate. Check the qualifying care or supervision needs and how other funding affects payment before applying.
Paying privately
Most families arranging live-in care pay privately, often from savings, pensions and Attendance Allowance together. Before making large financial decisions, such as releasing equity from a home, speak to an independent adviser. The Society of Later Life Advisers (SOLLA) lists accredited advisers who specialise in care funding.
Where to start this week
- Apply for Attendance Allowance on GOV.UK if your relative does not already receive it.
- If health needs are complex, ask the GP or district nurse for a CHC checklist.
- Ask the council's adult social care team for a needs assessment.
- Speak to an independent adviser before selling or borrowing against the home.
Where we fit
We do not give financial advice, but we can explain what a live-in carer can and cannot help with, which makes funding assessments easier, and point you to the right people.
Figures checked October 2026 and correct for England in 2026/27. Sources: DHSC charging circular 2026/27; DWP benefit rates 2026/27; NHS: Continuing Healthcare; GOV.UK: Attendance Allowance rates.